Reading time:
9 min
Fund savings plan - what to be considered
A fund savings plan combines the benefits of a savings account with the return opportunities of financial markets for you. However, it’s also important to pay attention to costs and fees here. We have outlined the most important aspects for you in a comparison.
THE MOST IMPORTANT POINTS AT A GLANCE:
A fund savings plan helps you invest even small savings amounts into funds
Returns of 4% to 7% are realistic
Pay attention to fees when choosing a provider; 1% is clearly too expensive
Simple and transparent investment solutions are to be preferred
Index
What is a fund savings plan?
With a fund savings plan, you can start investing with small amounts. Instead of letting your savings sit in your account (earning zero interest), you can invest in the financial market this way. And benefit from attractive long-term returns. The investment is made through an investment fund. An investment fund is a collective investment that pools funds from many investors to invest them collectively in the financial or capital markets.
Additionally, the fund savings plan is also very suitable if you want to invest additional funds regularly and systematically. This applies especially to smaller amounts, ranging from a few hundred to a few thousand Swiss francs.
How does a fund savings plan work?
First, you decide on your preferred provider, usually a bank or a wealth manager. Then, you open an account there. Make sure to prioritize transparency and fees when making your choice. After opening the account, which ideally can be done online, you select the investment strategy that suits you. Now you’re ready to make the first deposit. Once the transfer is received in the fund account, it will be invested according to the investment strategy you chose.
When selecting the investment strategy, the provider may offer you the option to adopt their investment funds tailored to your risk tolerance. Sometimes, you may also have the option to select your own investment funds. If you are investing in the financial market for the first time or have little interest in investment funds, it’s advisable to adopt the suggested funds. However, also pay attention to the costs in this case.
Difference between a savings account and a fund savings plan
With a savings account, your saved money practically sits idle on the account, earning minimal interest. It’s quite different with a fund savings plan. Here, your wealth is invested in the financial market and benefits from potentially higher long-term returns.
Both options offer excellent liquidity. With a savings account, you can easily make withdrawals at the bank counter or through an ATM. Or you can initiate a transfer to another account.
Fund savings plans and savings accounts also differ in terms of volatility. Volatility refers to the fluctuation in value. Savings accounts do not experience volatility. With a fund savings plan, the value of your savings changes according to the fluctuations in the chosen investment funds. In general, the higher the proportion of stocks, the greater the volatility. However, this also means potentially higher long-term wealth growth.
Comparison of a fund savings plan and a savings account
Savings Account | Fund Savings Plan | |
|---|---|---|
Value fluctuations | No | Yes |
Liquidity | Yes | Yes |
Direct Costs | Yes | Yes |
Inflation Protection | No | Yes |
Appreciation | No | Yes |
When is a fund savings plan sensible?
If you’re starting to save and regularly set aside additional funds, and you want your savings to work for you, then a fund savings plan is right for you.
A fund savings plan is also the perfect solution for your godchild or, of course, for your own offspring. A fund savings plan is an excellent choice as a godparent account because you’re saving money for your godchild over the long term.
A fund savings plan also makes sense if you don’t want to deal with stock market prices on a daily basis.
Additionally, you benefit from the average cost effect when regularly depositing into your fund savings plan.
What is the average cost effect?
There will always be times when the prices of your investments in the financial market both rise and fall. Additionally, no one always knows the right time to make an investment. When you regularly and consistently contribute to your fund savings plan, the average cost effect comes into play. One deposit of 500 Swiss francs occurs when the prices of the fund units are at historically high levels. For the fixed 500 Swiss francs, for example, you get 5 units. The next deposit of your 500 Swiss francs happens when the prices per fund unit have just experienced a temporary decline of 10%. So now you get 5.5 units for your 500 Swiss francs.
Therefore, with regular contributions, you no longer have to guess whether the financial markets are currently at a high or low. When prices are high, you automatically buy fewer units, but when prices are low, you get more. This smoothens out the average cost of acquisition.
Regular deposits or investing all at once?
Regular contributions within a fund savings plan help your investment portfolio grow into a substantial sum over the long term, even if you start with little money and a small amount. However, regularly investing smaller amounts also means you can start investing earlier. The earlier you start, the more you benefit from the long-term growth potential of financial markets and thus from the compounding effect.
How much interest (return) does a fund savings plan yield?
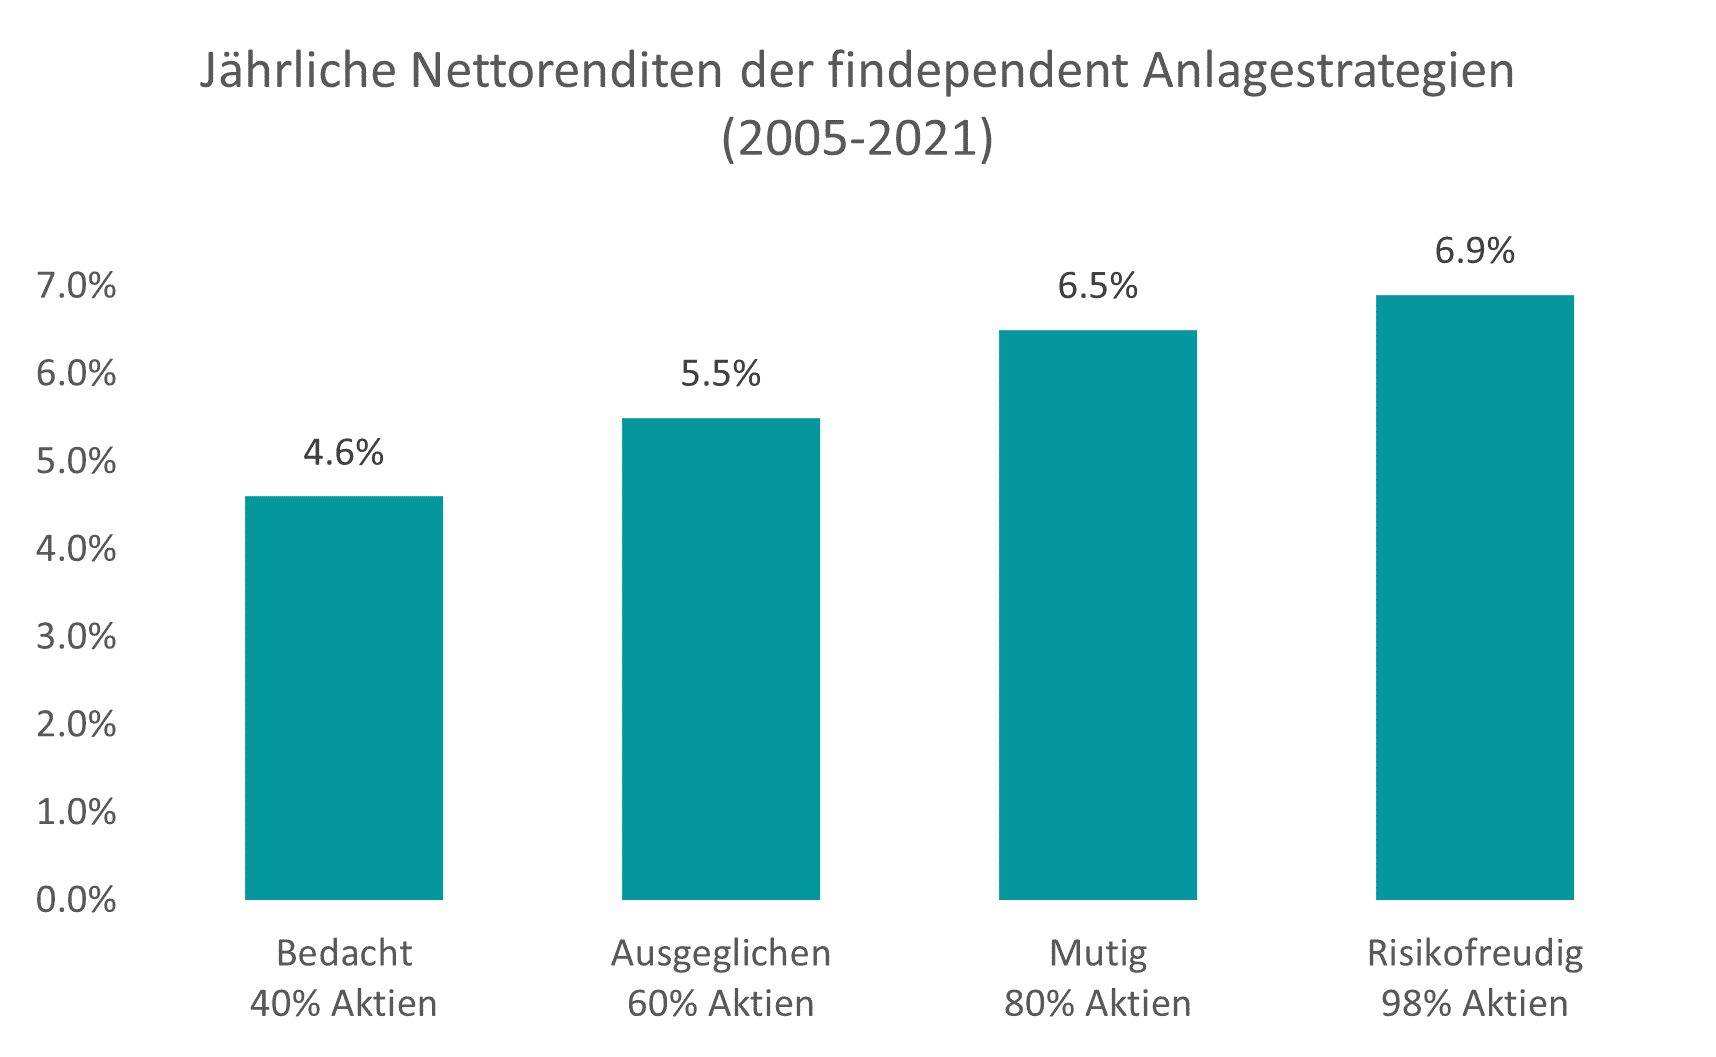
The interest rates, termed as returns in fund investments, vary depending on the fund or strategy you have chosen. The higher the equity component of your strategy, the higher the expected long-term return. In this table, along with further details provided here, you will find an overview of the returns of the strategies/investment solutions offered by findependent.
If you want to perform calculations yourself and incorporate your personal situation, feel free to play around with our return calculator:
Small deposits with significant impact
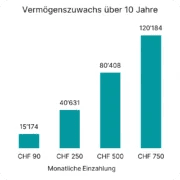
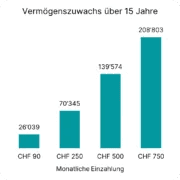
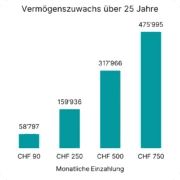
Even seemingly small contributions to your fund savings plan can, if made regularly and over the long term, grow into a substantial fortune. For example, with a monthly investment of 90 Swiss francs over a period of 10 years, you could accumulate around 15,000 Swiss francs. Investing 250 Swiss francs per month over 15 years could result in over 70,000 Swiss francs. And with a monthly deposit of 500 Swiss francs for 25 years, the wealth could grow to well over 300,000 Swiss francs.
Asset development with monthly deposits:
Monthly Deposit | Investment Duration | Investment Duration | Investment Duration |
|---|---|---|---|
CHF 90 | 15’174 | 26’039 | 58’797 |
CHF 250 | 40’631 | 70’345 | 159’936 |
CHF 500 | 80’408 | 139’574 | 317’966 |
CHF 750 | 120’184 | 208’803 | 475’995 |
The displayed returns are based on an annual return of 5.5% (net) with an initial capital of CHF 500 and with advance payments.
Which investment fund is suitable for my fund savings plan?
In principle, most types of investment funds are suitable for your fund savings plan. It could therefore also be called an investment fund savings plan. However, the term is a bit cumbersome. Equity funds, bond funds, money market funds, investment strategy funds, all are generally possible. Unfortunately, banks often restrict the selection from the range of funds and sometimes only offer internally managed strategy funds. The latter often have high to very high management fees. In contrast, index funds and exchange-traded funds (ETFs) can score with very low annual management fees. Therefore, you should look for a provider for your fund savings plan that also allows you to choose from cost-effective index funds or even ETFs.
What are the costs of a fund savings plan?
In addition to annual management fees, investing in funds in Switzerland incurs costs in the form of custody fees (also annual) and stamp duties (with each transaction). Additionally, some providers charge entry fees for investment. However, there are no entry fees for ETFs. The fees for managing a fund savings plan with passive funds (ETFs) should be between 0.5% and 0.8%. Custody fees range from 0.1% to 0.3% and are already included in the management fee with attractive providers. Unfortunately, it is still the case that many banks use fund savings plans to sell investment funds (which are pro forma actively managed) with excessive fees. Anything over 1% is rather expensive and should be avoided.
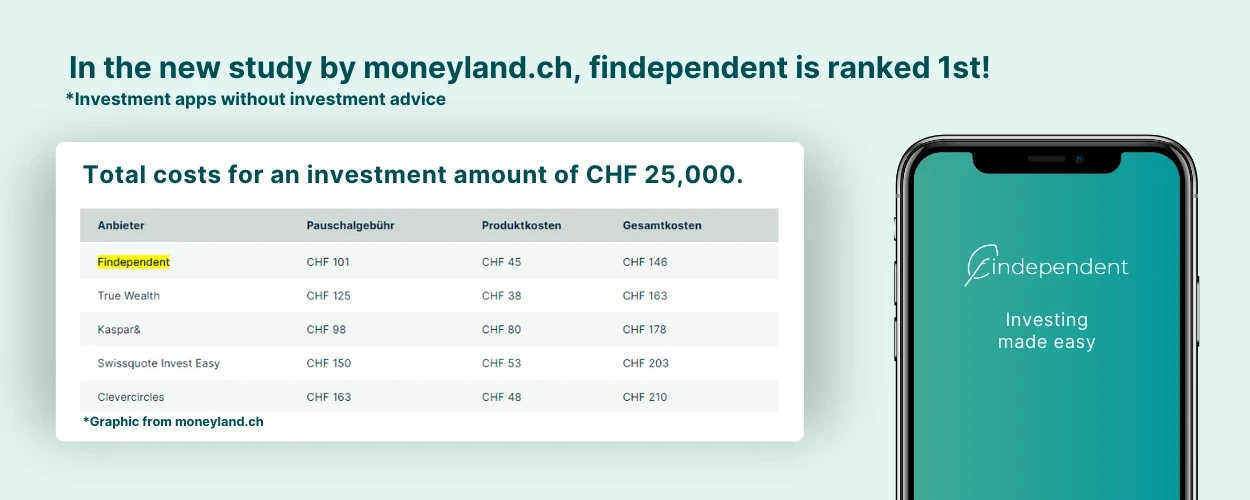
The independent comparison portal moneyland.ch found that digital investment apps are significantly cheaper than traditional asset managers. You can find the entire study here.
Best fund savings plan in Switzerland
From an investor’s perspective, you should therefore not (only) focus on historical returns. Because past performance is not a guarantee of future results. The level of annual management fees also plays an important role. In addition, providers that offer low minimum investment amounts and thus make it easier for you to get started are suitable. Good to know: At findependent, you can start with as little as 500 Swiss francs. In addition, there are no management and custody fees for the first 2,000 Swiss francs invested. And that’s for life!
How do you find the most affordable fund savings plan?
If you simply opt for the first offer from your house bank, you almost certainly won’t get the best deal. The online comparison service Moneyland provided a good fee overview at the end of 2021.
The investment app from findependent provides you with everything you need in a simple and clear way: low minimum investment (CHF 500) and an ETF range with low fees (0.29-0.40% for both management and custody).
Conclusion on the fund savings plan
If you want to regularly set aside money and not just let it languish in a savings account, investing in funds or a fund savings plan is right for you. If you don’t believe in the added value of expensive active asset management, a cheap, passive solution with index funds and ETFs suits you. If you also prefer a fully automated and digital solution for your asset management, findependent is your best choice.
FAQ
The most frequently asked questions and answers
What is the difference between findependent and a broker like Swissquote or Saxo?
The main difference in one sentence: With a broker, you have to do everything yourself; with us, you get an all-inclusive, hassle-free package.
A broker (e.g., Swissquote or Saxo Bank): For the DIY investor:
You choose, buy, and sell all securities (stocks, crypto, etc.) entirely on your own. This gives you maximum freedom but also requires a lot of time, knowledge, and research. Ideal if you want to trade actively and bet on individual stocks.
findependent: The all-inclusive package:
You simply deposit money, and we take care of the rest. We create a professional, broadly diversified investment solution for you and monitor it. Ideal for long-term wealth accumulation without having to constantly worry about the markets.
The best of both worlds: Your custom findependent solution:
Want more say? Then build your own personal investment solution from our selection of around 40 pre-selected, high-quality ETFs. You benefit from our expertise while still having the freedom to set your own priorities.
You can find more information about the differences on our information page.
How does findependent select ETFs?
Our investment committee selects the ETFs for the five ready-to-go findependent investment solutions as well as for customizing an own investment solution according to the following criteria.
Basic requirements
SIX Listing:
We only buy ETFs that are tradable on the Swiss Stock Exchange (SIX). Transactions on foreign exchanges often entail additional costs for Swiss investors.
Offering for private clients in Switzerland:
For regulatory reasons, our customers are classified as such during the registration process and receive the corresponding legal rights. Consequently, certain products are not accessible to them.
Established providers:
We prefer UBS, BlackRock (iShares), and Vanguard. Running ETFs is a classic volume business, i.e. the more capital a provider manages, the lower its average costs and the lower the prices and better the performance it can offer. Therefore, there are few providers.
Fund domicile:
For ETFs with Swiss investments, we require the fund domicile to be Switzerland; for international investments, Ireland and Luxembourg. The jurisdiction in which an ETF holds its investments is particularly relevant for the tax treatment of distributions (dividend and coupon payments). Swiss investors pay income tax on these, and depending on the country, for example, all or part of the withholding tax cannot be reclaimed.
Replication method:
We exclusively use ETFs that actually hold the investments whose performance they track. We prefer ETFs that hold all the investments of the underlying index. This is known as "full physical" replication. The use of an "optimized method" is also possible. Conversely, we exclude the use of ETFs that replicate the underlying index using complex financial instruments ("synthetic" replication). These carry financial risks if their provider goes bankrupt.
Exotic features:
We do not buy ETFs that exhibit exotic features. On the one hand, these include currency hedging, short sales, and leverage for short-term speculation. Such products often have high hidden costs. We also distance ourselves from ETFs that implement an opaque quantitative strategy, such as multi-factor products or minimum-variance approaches. They are complex and often lack a robust track record.
Retrocessions:
We do not select any ETFs for which findependent receives compensation from the provider, but choose the ETFs independently.
Important selection criteria
TER:
We generally use ETFs with product costs (TER) that do not exceed 0.5% per year. The lower, the better, as lower product costs mean higher returns for investors. This is an important key figure.
Spread:
We only select ETFs that demonstrably have a lower average spread between the purchase ("ask") and sale price ("bid") than 0.5%. The narrower, the better, as wide bid-ask spreads mean excessively high purchase prices or excessively low sale prices, which directly results in lower returns for investors.
Size:
We prefer ETFs that manage more than CHF 100 million. A "small" ETF has similar costs to a "large" one, but generates less revenue, tends to have low trading volumes, and high spreads. This means higher costs for investors and carries the risk that the ETF will be closed if it lacks commercial success.
Age:
We prefer ETFs with a track record of at least three years. A "young" ETF often has low assets initially, low trading volumes, and high spreads. Once again, this carries the risk that the ETF will be closed if it lacks commercial success.
Tracking quality:
We preferably select ETFs whose performance continuously loses less than 0.5% per year against the underlying index. The lower the difference, the better, as underperformance means a lower return for investors. This is an important key figure.
In summary:
We only use established ETFs from leading providers.
There are no opaque financial structures hidden behind the ETFs used; instead, the assets are held directly.
All ETFs used have high trading volumes and can be bought or sold for you at any time.
We only use ETFs with low product costs (TER).
All ETFs used have high trading volumes and thus low trading spreads.
Passive investing with ETFs minimises transaction costs.
Our investment committee reviews the ETFs regularly and makes adjustments if better ones enter the market. By acting independently and keeping costs low, more stays in your pocket in the end.
Which findependent investment solution is right for me?
The right investment solution is as individual as your life! Which is why there is no single solution that fits everyone.
The good news: With findependent, everyone can find the right investment solution. And so you don't have to rack your brain over it for hours, we make it as easy as possible for you:
The app helps you choose: When opening your account, we ask you a few short questions in the app about your goals and risk tolerance. Based on your answers, the app automatically suggests the investment solution that best fits your profile.
Customize even further: Already have investing experience and want to tailor your investment solution even more? You can do that with us. With your own custom investment solution (from CHF 5,000), you can assemble your portfolio from around 40 preselected ETFs according to your own wishes and priorities.
Good to know:
Hold multiple investment solutions at the same time: You don't have to choose a single strategy for all your money! You can simply create multiple investment goals in the app – for example, a long-term goal "Retirement" with the "Risk-seeking" solution, and at the same time a "New car" goal with the "Cautious" solution or for your (god)child.
Nothing is set in stone: If your plans change, you can adjust your investment solution in the app at any time. And if you're ever unsure about your choice, you can book a free online consultation with our team at any time – we're happy to help!