Reading time:
6 min
Pillar 3a: Is it worth switching?
When was the last time you changed your smartphone? According to a Moneyland survey, 92 % of the Swiss population has done so at least once in the last ten years. When it comes to our main bank (37 %) or pillar 3a (40 %), however, we are much slower to move. Humans are creatures of habit after all. Honest answer: Are you a bit of a «change-phobe» too? Sure, unboxing a new smartphone is more fun at first than transferring your pillar 3a. And of course, that’s comparing apples with oranges to some extent. But it’s precisely this inertia with pillar 3a that could cost you many thousands of francs over the years. We’ll show you how easy it is to switch and how much money you can save in the process.
THE MOST IMPORTANT POINTS AT A GLANCE:
High fees eat up returns: Even small percentage differences in costs add up to five-figure franc amounts by the time you retire.
Cost trap (bank) funds: Some providers advertise low base fees but use tax-inefficient funds. Others use expensive traditional pension funds, sometimes even with hidden extra costs.
findependent is the price winner: Among all providers offering a fully tax- and cost-efficient investment solution, findependent offers Switzerland’s lowest price.
Switch in under 10 minutes: The transfer is straightforward and usually free of charge. You start it comfortably in the app, print service included.
Index
High costs reduce your retirement savings!
The compelling argument for switching your pillar 3a is cost. Costs continuously nibble away at your savings. What matters here is not annual percentages, but the actual amount in francs.
How high your personal savings potential is depends on four factors:
Transferable 3a assets: This is your entire previous pillar 3a balance (whether spread across 1 or 4 portfolios) that can be seamlessly transferred. Note: For funds pledged for mortgages or bound insurance policies, you must first clarify the details.
Annual contribution: How much you can deposit depends on your personal budget planning. The maximum legal amount is adjusted regularly.
Age: Written in black and white in your passport. The higher it is, the shorter your investment horizon within pillar 3a, and the less time you have to benefit from the cost advantages of a top-class solution.
Return potential: Not every investment solution is the same. If you have a long investment horizon and can ride out short-term fluctuations, strategies with a high equity component offer the best long-term return opportunities.
At findependent, you pay management fees of 0.29% per year, the lowest price in Switzerland for a fully tax- and cost-efficient pillar 3a investment solution. So you can really save money by switching.
How much you can save
Leave your calculator in the drawer! With our interactive fee calculator, you can calculate your savings in just a few seconds:
Simply adjust the sliders to your situation. Our calculator distinguishes between the two most common provider groups on the market:
Traditional pension funds (average 1.1 %): These include offers from UBS, PostFinance, Raiffeisen, or cantonal and regional banks. They usually package Pillar 3a into classic strategy funds with total costs exceeding 1 % per year.
Digital providers (average 0.45 %): These include app solutions like finpension, VIAC, frankly, neon, True Wealth, Selma Finance, Alpian, or Finpact.
Two real-life examples
These two scenarios show that switching is worthwhile for very different life situations:
Example 1: Julia (30 years old)
Julia has been saving with a digital provider in an 80 % equity strategy for five years. Her portfolio currently stands at around 45'000 francs. She plans to continue paying in the maximum amount every year.
Is a switch worth it for her?
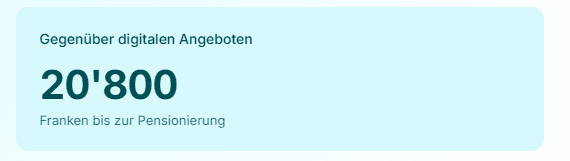
Yes, definitely! By switching to findependent, Julia saves over 20'000 francs in pure fees by the time she retires. The seemingly small percentage difference compared to her previous digital provider adds up over the decades to an impressive amount that she will have extra in her account at age 65.
Example 2: Philipp (47 years old)
Philipp has been providing for retirement for 20 years. His three portfolios are with his main bank in various pension funds with an average equity share of 60%. In total, 150'000 francs have already accumulated. Until retirement, he would like to pay another 5'000 francs annually into his pillar 3a.
Is a switch worth it for him?
Yes, absolutely! By switching to findependent, Philipp saves around 39'000 francs until his retirement. Although he is closer to retirement than Julia, his savings potential is even higher due to his existing balance and the high price tag of his pension funds.

In principle: Your savings potential is higher the larger your initial investment capital, the higher your future deposits, the younger you are, and the higher your chosen equity component.
Have we convinced you?
7 myths about switching Pillar 3a fact-checked
Still hesitating? You’re not alone. Many persistent prejudices circulate around switching Pillar 3a. We’re clearing them up:
Myth #1: «Changing providers is tedious and takes forever»
The opposite is true: There is hardly any financial product that you can switch more easily. All you need is 10 minutes. You don’t even have to call your current provider. Simply send them a signed transfer request by post.
There are no minimum contract terms or fixed cancellation periods like with health insurance. You can transfer your balance to a cheaper provider at any time (exception: pledged 3a).
The actual transfer and reinvestment are handled by the foundations in the background. Usually, the switch takes just a few days, though in rare cases it can take a few weeks.
Extra tip: If you have set up a standing order for your payments, you only need to adjust the IBAN to your new findependent 3a portfolio held with an account-holding securities firm.
Myth #2: «A switch costs a lot of money»
The pure capital transfer from one pension foundation to another is completely free of charge at almost all banks. It has become industry standard not to charge fees for closing a 3a savings account or paying out funds.
Exceptions exist mainly for bound insurance policies and 3a loans/mortgages. Asking in advance will help you avoid unpleasant surprises.
If your current bank charges a redemption fee when selling existing pension funds, you will usually break even on these one-time expenses after just a few months thanks to findependent’s extremely low Management fees of 0.29 %.
Myth #3: «A switch triggers taxes»
No. A transfer between two pillar 3a foundations is not a taxable withdrawal. The balance only becomes subject to tax upon final withdrawal in old age or under a few legally defined exceptions.
Myth #4: «Money with digital providers is less secure than with a main bank»
A clear no. The age of a provider says nothing about its security. All pillar 3a pension foundations in Switzerland are subject to the same strict legal requirements and regulatory supervision.
In addition, your investments qualify as special assets: They are legally protected with a separate pension foundation and completely separated from the provider’s operations. Even if the provider were to go bankrupt, your investments remain fully protected.
Myth #5: «During the switch, I miss out on market opportunities»
During the transfer, existing investments are sold and transferred as cash. For these few days, you are not invested in the market.
Whether prices rise or fall during these few days is impossible to predict. Looking at decades, however, this short moment plays no role in your investment success.
Myth #6: «I am only allowed to have a single pillar 3a account»
Not true. You are legally allowed to hold multiple 3a portfolios (in practice, up to 5 portfolios have proven ideal for most people). We have written a detailed article on this.
Multiple portfolios are actually clever: When drawing benefits later from age 60, you can liquidate the portfolios staggered over different years. This breaks the tax progression («the higher the sum, the higher the tax rate») and saves you a lot of money on capital withdrawal tax.
Extra tip: It’s best to start managing multiple portfolios early so that they have similar balances before retirement.
Myth #7: «All pillar 3a offers are basically the same»
Looking closely reveals huge differences in prices and included services. We have made a detailed comparison on this.
Digital providers like findependent, finpension, frankly, and VIAC performed best, offering fully tax- and cost-efficient investment solutions at low prices. In comparison, providers with expensive bank funds or tax-inefficient funds will cost you significantly more over the years.
How easy it is to switch to findependent
Ready for higher returns on your retirement savings? The switch works in just a few steps:
Download the app: Get the findependent app on your smartphone.
Open an account: Register digitally in under 10 minutes.
Choose a strategy: Select the matching investment solution for your Pillar 3a portfolio.
Start transfer: Create your transfer order directly in the app.
Send it off: Print out the application (or let us send it to you for free), sign it, and send it to your current provider.
We handle all the rest for you!
Would you like to discuss your personal situation first with no obligation? Our team is always happy to assist you.