Reading time:
7 min
Pillar 3a Providers in Comparison
A lot has happened since pension savings via Pillar 3a launched in 1987. What started with classic retirement savings accounts at banks evolved in the 90s into pension funds with high product costs. In 2017, the first app-based solution finally followed. Today, you have a huge range of options to choose from, making it easy to lose track. But watch out: not every option is attractive, and the devil is often in the detail. We are here to help you decide and show you why findependent offers the most attractive deal for you!
THE MOST IMPORTANT POINTS AT A GLANCE:
The Pillar 3a market offers plenty of options, but all that glitters is not gold.
The biggest differences lie in total costs, fund tax efficiency, and feature availability.
Beware of cheap yet inefficient offers using ETFs, or expensive traditional pension funds.
findependent offers the most affordable Pillar 3a deal among all providers focusing on a fully tax- and cost-efficient solution. That means more returns left for you!
Index
In short: The ranking among optimized solutions
We know what you want: a top-class investment solution with all the features at the lowest price.
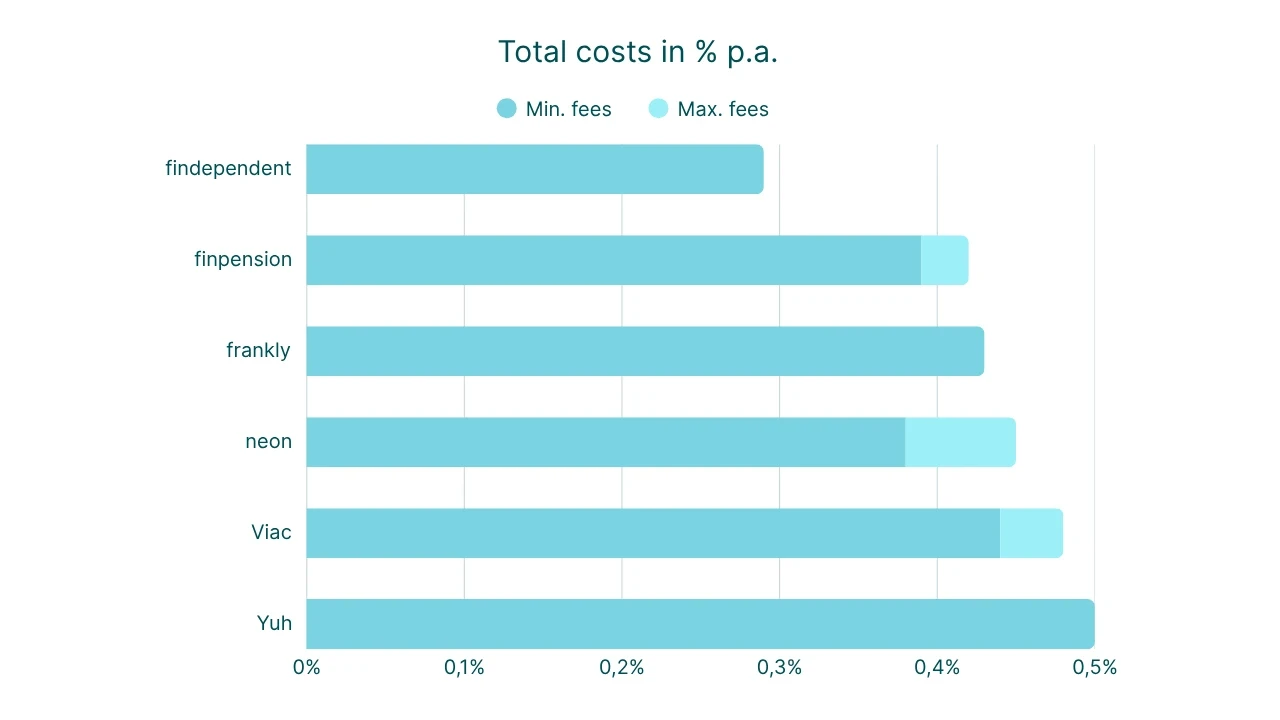
The following chart compares the prices of the standard strategies from the six best offers on the Swiss market:
*Data according to provider websites, as of October 2026
Conclusion: findependent is the most affordable Pillar 3a provider among all competitors offering you a truly efficient solution.
Why do we emphasize this? We deliberately compare ourselves only with providers that rely exclusively on tax-optimized index funds – because that’s the only way to build wealth optimally over the long term.
Well-known providers like TrueWealth, Selma Finance, or Alpian don't do this: they rely entirely or partially on ETFs, which bring significant cost disadvantages in Pillar 3a. And traditional banks like UBS, Raiffeisen, or PostFinance simply charge way too much with pension funds often well over 1% per year.
Let’s take a look at the details in this comparison!
How to compare best
The best investment solution combines full performance with the lowest prices. After all, your goal is a high net return on your pension capital. Keep a close eye on these criteria when comparing:
Costs:
Management fees: This is the part the provider charges for its service.
ETF costs (TER): Depending on which funds are used, these costs differ. We rely on special «pension index funds» that were developed exclusively for Swiss pension institutions and have no TER.
Additional costs: When normal funds or ETFs are used in Pillar 3a, additional costs arise: unrecovered withholding taxes, Currency conversion fees, as well as Stock exchange fees & stamp duties, and trading spreads (difference between buying and selling price).
Feature scope:
Tax-optimized index funds: These funds are exempt from withholding taxes on distributions such as dividends and interest payments. Swisscanto marks these with the abbreviation "IPF" in the product name, especially for investments in the US and Japan. Anyone avoiding these funds gives away returns.
No ETFs: ETFs are traded on the stock exchange and cause additional costs with every purchase (such as stamp duties). They are therefore inefficient in Pillar 3a. The numerous cost elements (see above) add up.
Minimum investment amount: Good offers start from as little as 1 franc. Higher minimum amounts indicate that ETFs are being traded.
Maximum equity allocation: The higher the possible equity share (up to the legal limit of 99%), the higher your long-term return opportunities. With offers that allow fewer equities, you give away long-term returns.
Number of portfolios: To save taxes when withdrawing later (breaking the tax progression), you should be able to maintain up to 5 portfolios.
Create your own investment solutions: Experienced investors appreciate the opportunity to customize their investment strategy individually.
Selection of investment focus: If you want to rely on ready-made investment solutions, you should be able to choose the right one from a selection. This includes strategies with a high Swiss Franc share and those with a global focus.
Own pension foundation: Offers with their own foundation have leaner processes and can therefore pass on better prices to you.
Transparent track record: You should be able to see at any time before opening how a strategy has developed in the past (track record) and what it consists of.
findependent offers the most affordable Pillar 3a investment solution...
Here you can see the detailed cost* breakdown:
findependent | finpension | frankly | neon | VIAC | Yuh | |
|---|---|---|---|---|---|---|
Annual Management fees | 0,29% | 0,39% | 0,43% | 0,38 - 0,45% | 0,40 - 0,44% | 0,50% |
ETF costs (TER) | 0% | 0% - 0,03% | 0% | 0% | 0% - 0,04% | 0% |
Currency conversion fees | no | no | no | no | yes (up to 0,75%) | no |
Hedging costs within funds | no | yes | yes | yes | no | yes |
Additional costs through ETF usage | no | no | no | no | no | no |
*Data according to provider websites, as of October 2026
The result: findependent's solutions have the lowest overall costs. Through the targeted use of tax-optimized index funds, we completely avoid hidden cost drivers.
... with the complete feature scope
Looking closely at the features* pays off too:
findependent | finpension | frankly | neon | VIAC | Yuh | |
|---|---|---|---|---|---|---|
Use of tax-optimized index funds | yes | yes | yes | yes (with caveats) | yes | yes (with caveats) |
No ETFs | yes | yes | yes | yes | yes | yes |
Minimum investment amount | CHF 1 | CHF 1 | CHF 1 | CHF 1 | CHF 1 | CHF 1 |
Maximum equity allocation | 99% | 99% | 95% | 99% | 99% | 98% |
Number of portfolios | 5 | 5 | 5 | 5 | 5 | 1 |
Custom investment solution | yes | yes | yes | no | yes | no |
Selection of investment focus | yes | yes | yes | yes | yes | no |
Own pension foundation | yes | yes | yes | no | yes | no |
Transparent track record | yes | yes | yes | no | yes | no |
*Data according to provider websites, as of October 2026
The comparison clearly shows two camps:
findependent, Viac, finpension, and frankly offer the full package. Only frankly slightly limits the maximum equity ratio to 95%.
Yuh and neon show gaps: they do not use tax-optimized funds for US and Japanese equities (costing you about 15% of dividends), offer no way to build custom strategies, show no track record on their website, and lack their own foundation structures. account-holding securities firm partner structures can also play a role here.
Watch out for inefficient or opaque solutions
Providers like TrueWealth, Selma Finance, or Alpian often seem cheap at first glance. However, they bring two major drawbacks:
ETFs as cost drivers: Instead of consistently relying on tax-optimized index funds, they use ETFs exclusively (Selma Finance, Alpian) or partially (TrueWealth). Every purchase or sale incurs stamp duties (0.075% – 0.15%) and stock exchange fees. Added to this are non-recoverable withholding taxes on foreign dividends (up to 15%) and potential Currency conversion fees. In a global equity strategy, you quickly lose up to 0.3% return per year simply through hidden costs.
«Blackbox» strategies: None of these providers transparently disclose the exact composition, management, or historical performance (track record). So you are buying a pig in a poke and can hardly compare the offers in advance.
Additionally, important features are often missing: Selma and Alpian only allow 1 portfolio (preventing future tax savings), and TrueWealth likely requires a minimum deposit of 1’000 francs due to its ETF structure.
Bank offers are very expensive
Classic bank offers from UBS, Raiffeisen, or PostFinance usually offer good basic features (like 5 portfolios and transparent reports).
The big problem is the price: no traditional provider offers a total solution for under 1% per year. Even if providers like PostFinance or Raiffeisen waive an explicit management fee, they «hide» high costs inside their in-house pension funds as TER. At Raiffeisen, issue surcharges may even be added depending on the cooperative.
If fair prices and high net returns matter to you, you're much better off with a digital solution!
What speaks for the findependent Pillar 3a investment solution
We stay true to our philosophy: Simple, transparent, and affordable
Simple: Choose from 15 ready-made strategies broadly diversified with 6 to 11 tax-optimized index funds.
Transparent: You can see anytime in the app how your money is invested, how it develops, and what costs apply.
Affordable: You get all this at Switzerland's top price: for an all-in fee of just 0.29% p.a.
What you need to do to switch
Download the app: Get the findependent app on your smartphone.
Open an account: Register digitally in under 10 minutes. Choose a strategy: Select your ideal investment solution for your first Pillar 3a portfolio.
Start the transfer: Create your transfer request directly in the app.
Send it off: Print the transfer request (or have us send it to you by post for free), sign it, and send it to your previous provider.
We take care of all the rest for you!